CLASSIFICAÇÃO FISCAL · NCM
2201.10.00
3.457 produtos cadastrados
Águas minerais e águas gaseificadas. Classificação fiscal do NCM 2201.10.00.
⚠ As informações fiscais são exibidas para consulta e devem ser validadas pelo responsável tributário da empresa.
Carga tributária média — IBPT
Federal (nacional)
13.88%
Federal (importado)
22.81%
Estadual (média UF)
22.94%
Municipal
0.00%
Ver por estado (UF)
| UF | Federal nac. | Federal imp. | Estadual | Municipal |
|---|---|---|---|---|
| AC | 14.29% | 20.87% | 25.00% | 0.00% |
| AC | 13.45% | 20.03% | 25.00% | 0.00% |
| AC | 13.45% | 20.03% | 25.00% | 0.00% |
| AL | 15.98% | 31.77% | 29.00% | 0.00% |
| AL | 13.45% | 29.24% | 29.00% | 0.00% |
| AL | 13.45% | 29.24% | 29.00% | 0.00% |
| AM | 14.43% | 21.77% | 20.00% | 0.00% |
| AM | 13.45% | 20.79% | 20.00% | 0.00% |
| AM | 13.45% | 20.79% | 20.00% | 0.00% |
| AP | 14.90% | 24.77% | 18.00% | 0.00% |
| AP | 13.45% | 23.32% | 18.00% | 0.00% |
| AP | 13.45% | 23.32% | 18.00% | 0.00% |
| BA | 14.25% | 20.59% | 27.00% | 0.00% |
| BA | 13.45% | 19.79% | 27.00% | 0.00% |
| BA | 13.45% | 19.79% | 27.00% | 0.00% |
| CE | 15.11% | 26.15% | 30.00% | 0.00% |
| CE | 13.45% | 24.49% | 30.00% | 0.00% |
| CE | 13.45% | 24.49% | 30.00% | 0.00% |
| DF | 14.26% | 20.67% | 26.00% | 0.00% |
| DF | 13.45% | 19.86% | 26.00% | 0.00% |
| DF | 13.45% | 19.86% | 26.00% | 0.00% |
| ES | 14.78% | 24.02% | 17.00% | 0.00% |
| ES | 13.45% | 22.69% | 17.00% | 0.00% |
| ES | 13.45% | 22.69% | 17.00% | 0.00% |
| GO | 14.01% | 19.06% | 7.00% | 0.00% |
| GO | 13.45% | 18.50% | 7.00% | 0.00% |
| GO | 13.45% | 18.50% | 7.00% | 0.00% |
| MA | 15.98% | 31.77% | 30.50% | 0.00% |
| MA | 13.45% | 29.24% | 30.50% | 0.00% |
| MA | 13.45% | 29.24% | 30.50% | 0.00% |
| MG | 15.17% | 26.52% | 25.00% | 0.00% |
| MG | 13.45% | 24.80% | 25.00% | 0.00% |
| MG | 13.45% | 24.80% | 25.00% | 0.00% |
| MS | 14.79% | 24.09% | 30.00% | 0.00% |
| MS | 13.45% | 22.75% | 30.00% | 0.00% |
| MS | 13.45% | 22.75% | 30.00% | 0.00% |
| MT | 14.70% | 23.50% | 17.00% | 0.00% |
| MT | 13.45% | 22.25% | 17.00% | 0.00% |
| MT | 13.45% | 22.25% | 17.00% | 0.00% |
| PA | 14.56% | 22.60% | 19.00% | 0.00% |
| PA | 13.45% | 21.49% | 19.00% | 0.00% |
| PA | 13.45% | 21.49% | 19.00% | 0.00% |
| PB | 14.21% | 20.35% | 20.00% | 0.00% |
| PB | 13.45% | 19.59% | 20.00% | 0.00% |
| PB | 13.45% | 19.59% | 20.00% | 0.00% |
| PE | 14.52% | 22.32% | 18.00% | 0.00% |
| PE | 13.45% | 21.25% | 18.00% | 0.00% |
| PE | 13.45% | 21.25% | 18.00% | 0.00% |
| PI | 14.95% | 25.13% | 29.00% | 0.00% |
| PI | 13.45% | 23.63% | 29.00% | 0.00% |
| PI | 13.45% | 23.63% | 29.00% | 0.00% |
| PR | 14.29% | 20.86% | 19.00% | 0.00% |
| PR | 13.45% | 20.02% | 19.00% | 0.00% |
| PR | 13.45% | 20.02% | 19.00% | 0.00% |
| RJ | 14.61% | 22.90% | 18.00% | 0.00% |
| RJ | 13.45% | 21.74% | 18.00% | 0.00% |
| RJ | 13.45% | 21.74% | 18.00% | 0.00% |
| RN | 15.42% | 25.98% | 29.00% | 0.00% |
| RN | 13.45% | 24.01% | 29.00% | 0.00% |
| RN | 13.45% | 24.01% | 29.00% | 0.00% |
| RO | 14.86% | 24.52% | 39.00% | 0.00% |
| RO | 13.45% | 23.11% | 39.00% | 0.00% |
| RO | 13.45% | 23.11% | 39.00% | 0.00% |
| RR | 14.62% | 22.98% | 25.00% | 0.00% |
| RR | 13.45% | 21.81% | 25.00% | 0.00% |
| RR | 13.45% | 21.81% | 25.00% | 0.00% |
| RS | 14.11% | 19.68% | 17.00% | 0.00% |
| RS | 13.45% | 19.02% | 17.00% | 0.00% |
| RS | 13.45% | 19.02% | 17.00% | 0.00% |
| SC | 14.94% | 25.04% | 17.00% | 0.00% |
| SC | 13.45% | 23.55% | 17.00% | 0.00% |
| SC | 13.45% | 23.55% | 17.00% | 0.00% |
| SE | 15.98% | 31.77% | 21.00% | 0.00% |
| SE | 13.45% | 29.24% | 21.00% | 0.00% |
| SE | 13.45% | 29.24% | 21.00% | 0.00% |
| SP | 13.94% | 18.59% | 18.00% | 0.00% |
| SP | 13.45% | 18.10% | 18.00% | 0.00% |
| SP | 13.45% | 18.10% | 18.00% | 0.00% |
| TO | 14.27% | 20.71% | 29.00% | 0.00% |
| TO | 13.45% | 19.89% | 29.00% | 0.00% |
| TO | 13.45% | 19.89% | 29.00% | 0.00% |
Fonte: IBPT (Instituto Brasileiro de Planejamento e Tributação) — versão 23.2.E. Percentuais aproximados de tributos sobre o NCM 2201.10.00, para referência. A carga real depende do regime tributário, da operação e da UF — valide com o responsável tributário.
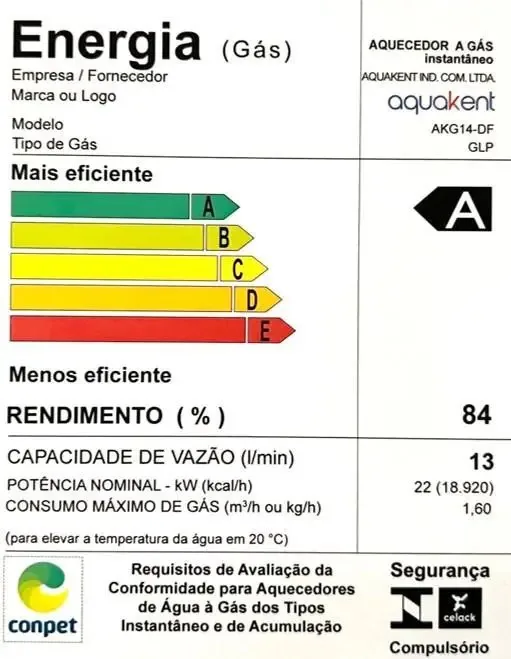
Aquecedor De Aguas A Gás Aquakent 14l Cinza
6939962583044Aquakent· NCM 22011000
Arena De Dados Black Premium
7898664125664Bucaneiros Jogos· NCM 22011000

Armacao Carmim - Crm41598 C2
7899976674338Carmim· NCM 22011000
Aro E Tampa Pedal Comando Ar Progressivo Equipo Odontológico
7892416541054Genérica· NCM 22011000

Arrancador Ramada Inco Jardim 6829
7896438068292Ramada· NCM 22011000
Auricular Hye Hye2a Bluetooth - Blanco
7793323788795HYE· NCM 22011000

Bacia Japi Europa Jveoc55 Cimento
7894023059946Geral· NCM 22011000
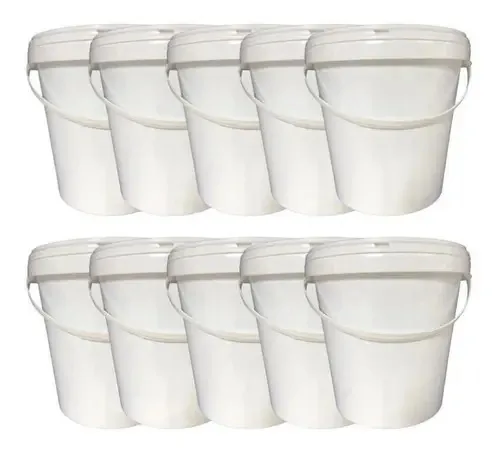
Bal 3.6l Alça Plast Plastico
7898395215337Nastripack· NCM 22011000
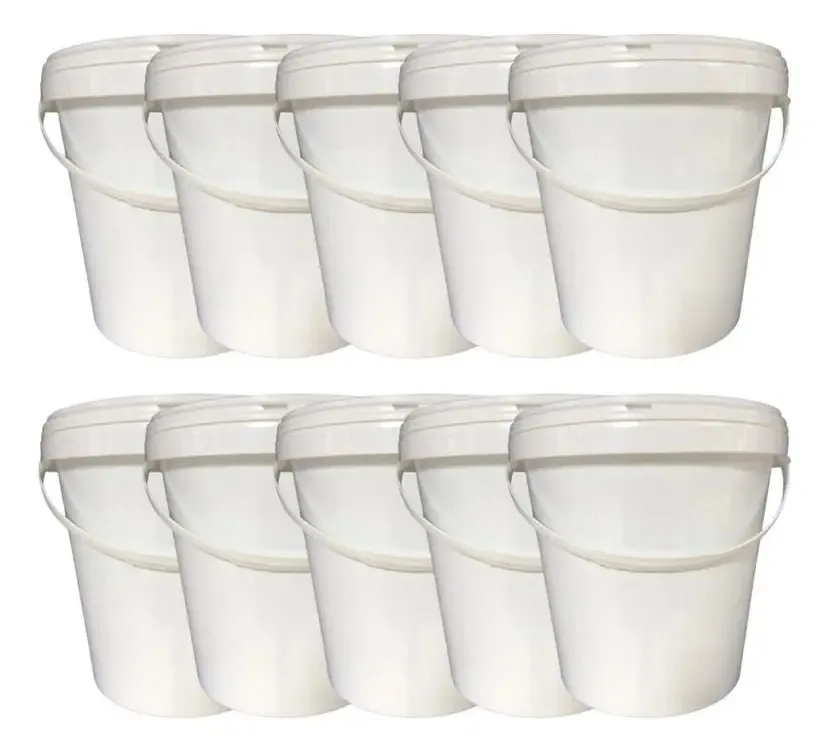
Bal Plast 3.6l Alça Plast P Alimentos Frescos
7898395211544Nastripack· NCM 22011000
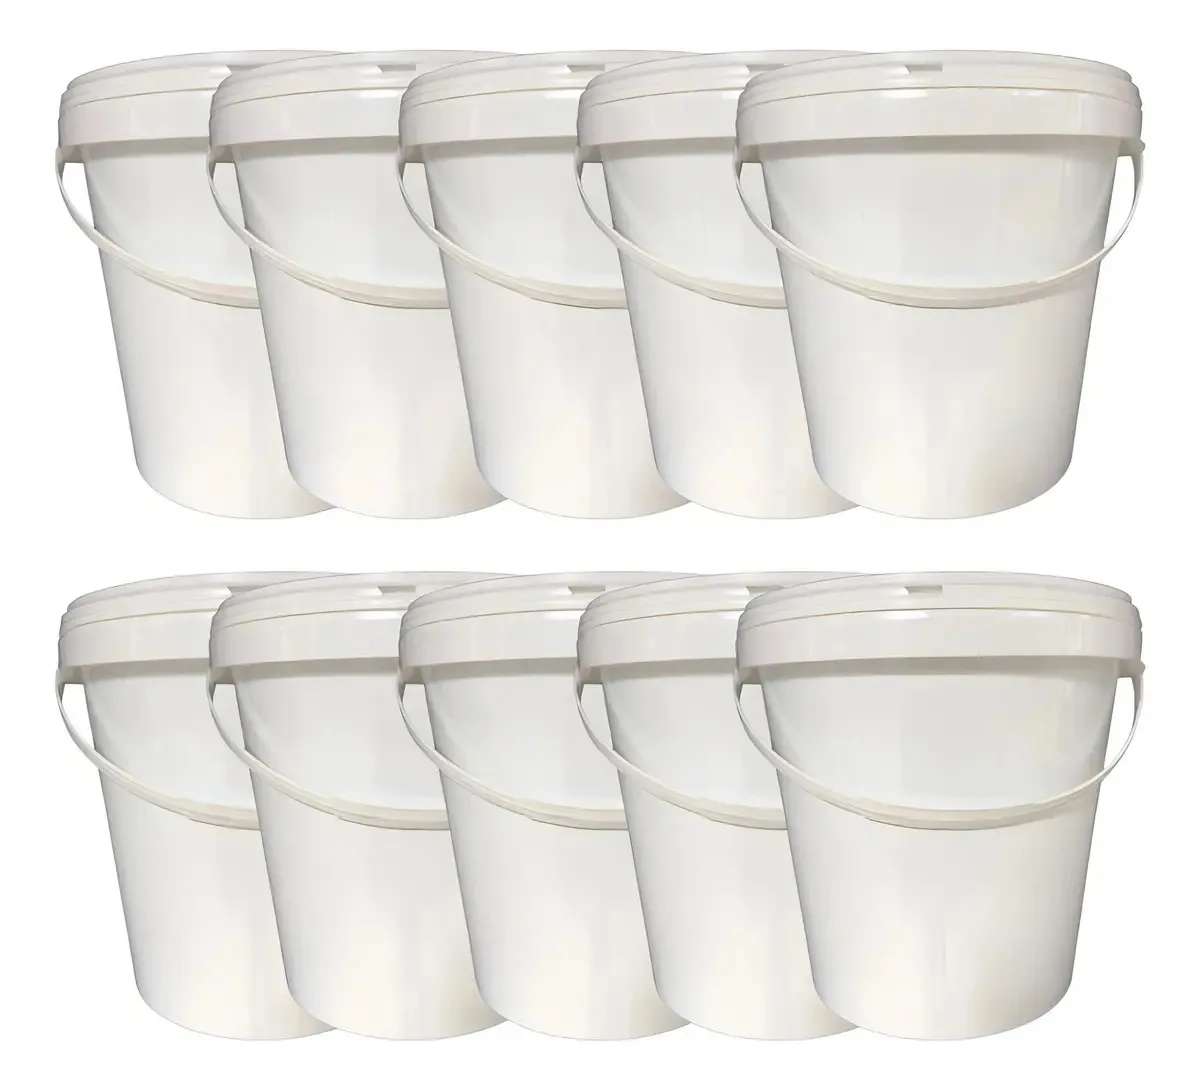
Bal Plast 3.6l Alça Plast P Carnes E Tampa Removível
7898395210356Nastripack· NCM 22011000

Bal Plast 3.6l Alça Plast P Cosméticos E Tampa Removível
7898395210431Nastripack· NCM 22011000

Bal Tampa 3.6l Alça Plast
7898395216020Nastripack· NCM 22011000
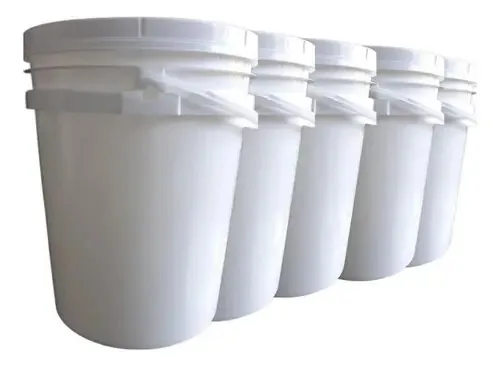
Bald 20l Alça Plástica Plastico
7897999531836Nastripack· NCM 22011000
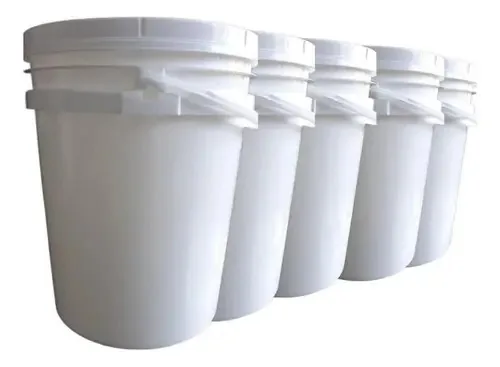
Bald P Confeitaria D 20l E Tamp Lacre
7897999518622Nastripack· NCM 22011000
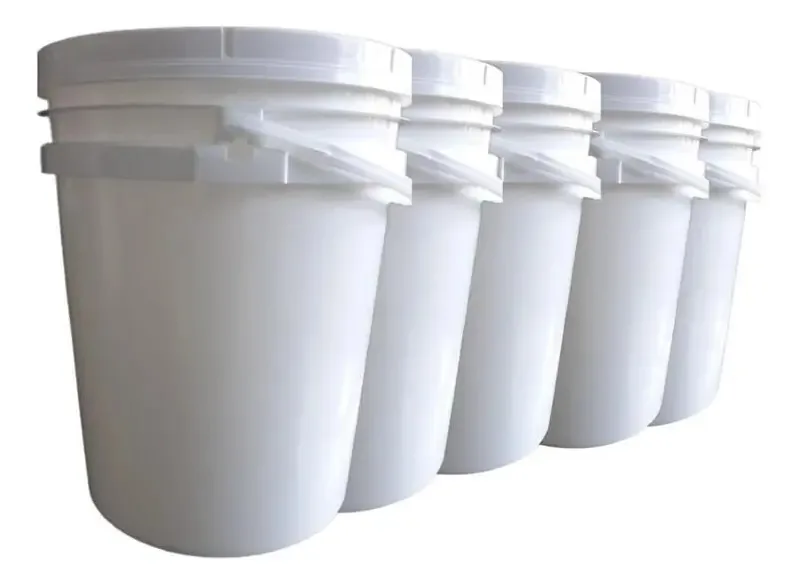
Bald P Embalagem 20l E Tamp Lacre
7897999517748Nastripack· NCM 22011000
Bald Plast 20l Alç Plast P Embutidos E Tamp Removível
7897999520366Nastripack· NCM 22011000
Bald Plast 20l C Tamp
7897999516239Nastripack· NCM 22011000
Bald Plast 20l D Lixo
7897999510473Nastripack· NCM 22011000

Bald Plast 20l P Carregamento
7897999516918Nastripack· NCM 22011000
Bald Plast 20l P Estufa
7897999516598Nastripack· NCM 22011000
Bald Plast 20l P Granola
7897999515720Nastripack· NCM 22011000
Bald Plast 20l P Quentinha
7897999515980Nastripack· NCM 22011000
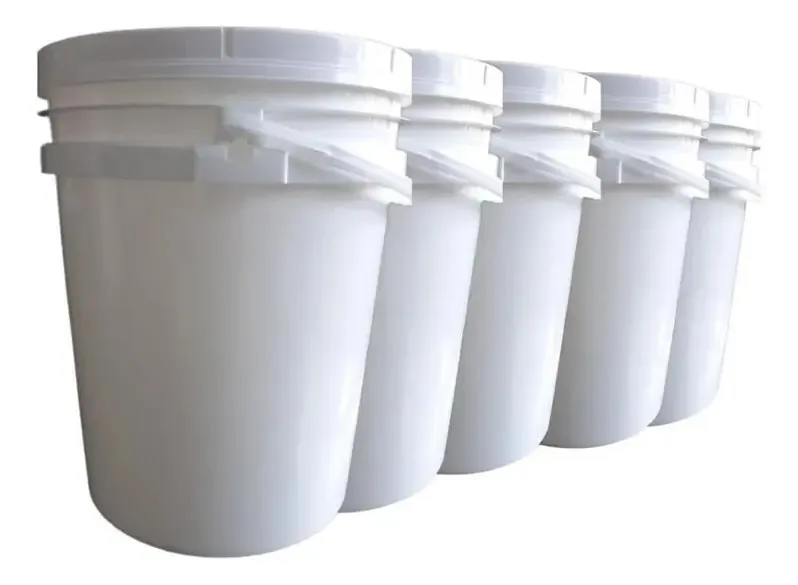
Bald Plast 20l P Água
7897999516253Nastripack· NCM 22011000
Bald Plast 20l Para Equino
7897999510589Nastripack· NCM 22011000
Perguntas frequentes
O que é o NCM 2201.10.00?
O NCM 2201.10.00 é um código da Nomenclatura Comum do Mercosul usado para classificar a mercadoria para fins fiscais e aduaneiros.
Como validar a classificação fiscal deste NCM?
A classificação fiscal deve ser validada pelo responsável tributário da empresa, considerando a natureza exata do produto e a legislação vigente.